I’ve been wanting a 3D printer for years. The model I’m looking to purchase is around 10k.
While I technically have the means to afford it, it also means adding another “thing” in my life. There will be a mental burden to get the most out of it, and there will be guilt if I end up not using it as much.
Whenever I consider purchasing something for myself, there is always a lot to consider. I’m very frugal when it comes to things.
On the other hand, dining out with family or friends, particularly in larger groups, can easily reach the same cost. In those cases, I don’t even hesitate to cover the bill.
The key difference is I’m spending on people.
I feel like time spent together is always worth it, regardless of the cost.
This phrase encapsulates my general approach to spending: generous on people, frugal on things
There are other ways I try to be generous on people:
Always giving tip for any service, knowing that an unexpected extra income might help to the person that served me
Gifting things for people that has the potential to make their lives better
Appreciate people helpful to me and/or my family
Giving when opportunity of kindness presents itself
I haven’t done budgeting since November 2022 (9 months!). Mainly because I’m
out of track.
Before getting out of track, I’ve been consistently doing it for the past 5
years.
I’ve attempted twice to get my budget in order, but the backlog is just too
much. There’s a lot to account for, there’s a lot to tally. After spending
several hours hours backtracking, I gave up.
Fresh start
YNAB has this
concept of not caring about past expenses. There’s nothing you can do with
money already spent.
Even though it’s good to have 5 years worth of data, it’s only a nice-to-have.
If I continue to operate without a budget, I’m risking myself to be in a
position where I anxiously wait when my next paycheck will be. Kahig-tuka ba.
Another side-effect is it’s also getting incredibly difficult to make big
financial decisions without knowing where I stand financially.
I decided to let go and do a fresh start.
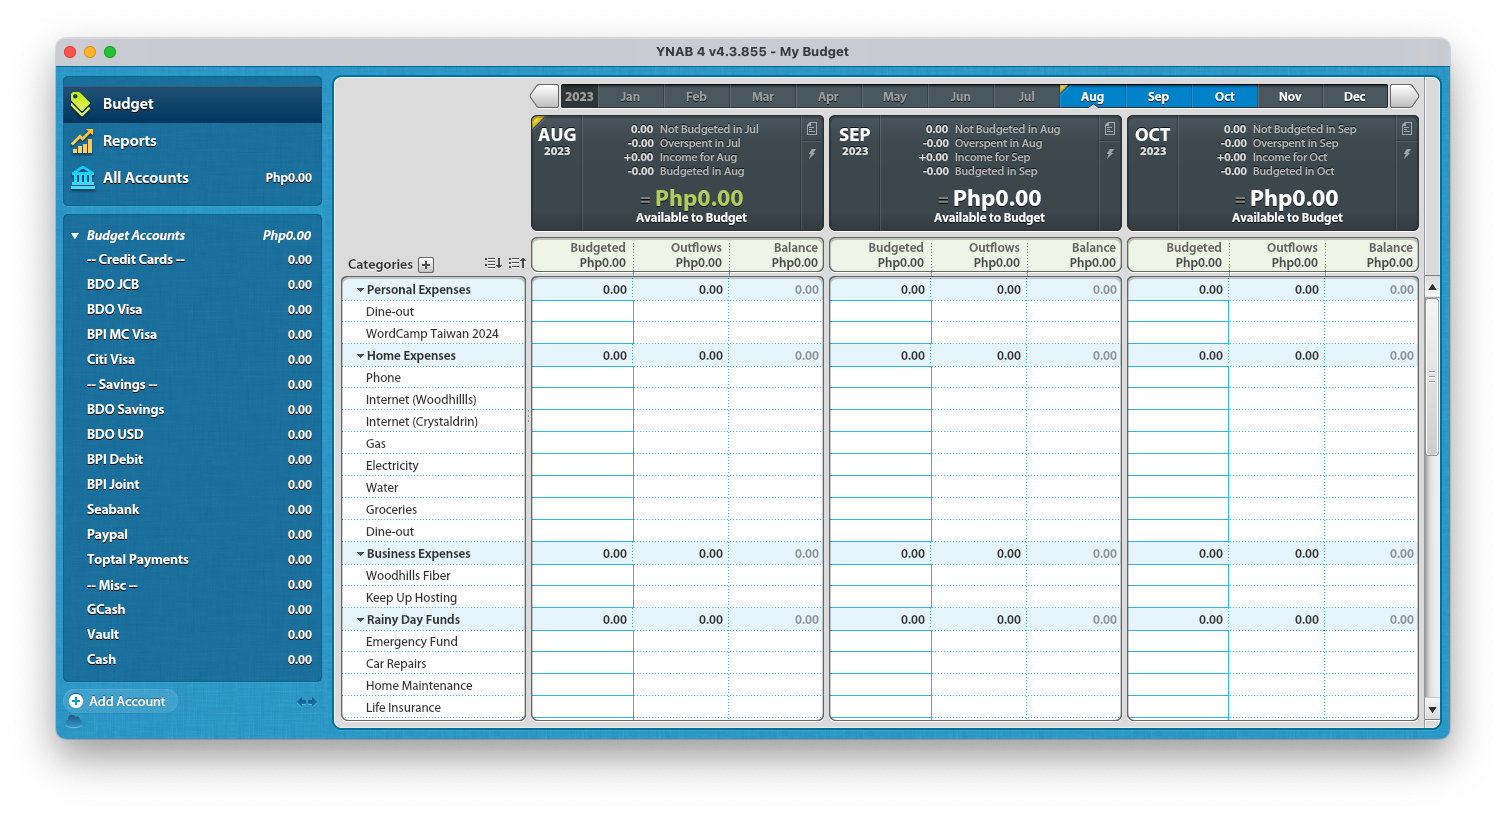
Switching back to Classic YNAB
Since I’m going to start fresh, it’s a perfect time to switch back to Classic
YNAB.
I love YNAB methodology. It fits my thinking. It helped me manage my money when
I started earning.
Over the years, the company behind YNAB changed and they pivoted the product to
one-time purchase to a monthly subscription. I had no problem with it,
especially with a grandfather’ed pricing where I got a discounted monthly fee.
I’m happy to pay because it literally changed how I think about money.
A couple of years more, they increased the price twice. It felt like they lock
you down with their methods, and leave you no choice but to accept their
pricing change.
It’s been on my list to move out of YNAB. I was looking for something that I
can use in my lifetime. I tried Firefly III (an
open-source alternative but with different methodology),
GnuCash (another open-source alternative), but the
YNAB method is already ingrained in me.
Luckily, I’m not alone feeling this way. The community made the classic YNAB 4
work on a modern OS.
Knowing for a fact that it will not change (it hasn’t been updated since 2019)
gives me confidence it will still work for the foreseeable future. I can build
my budgeting process without getting affected on any change of direction of the
company behind it.
Y64
Y64 provides a bash script that will
download the latest YNAB 4 and the latest Adobe AIR 64-bit runtime and compile
it to a working app. Running the script will output a working YNAB 4 app.
The app itself aged like a fine wine. It’s still perfectly usable and does not
feel old.
License
YNAB does not sell license anymore for the classic YNAB. Since it’s already
unsupported, the way to workaround this is to adjust the trial mode end-date by
editing the license file.
Growing up, I heard that investing in a real estate property and renting it out is a good investment. I didn’t understand why. Especially where the required capital is intimidatingly high, I couldn’t even imagine how to earn that much.
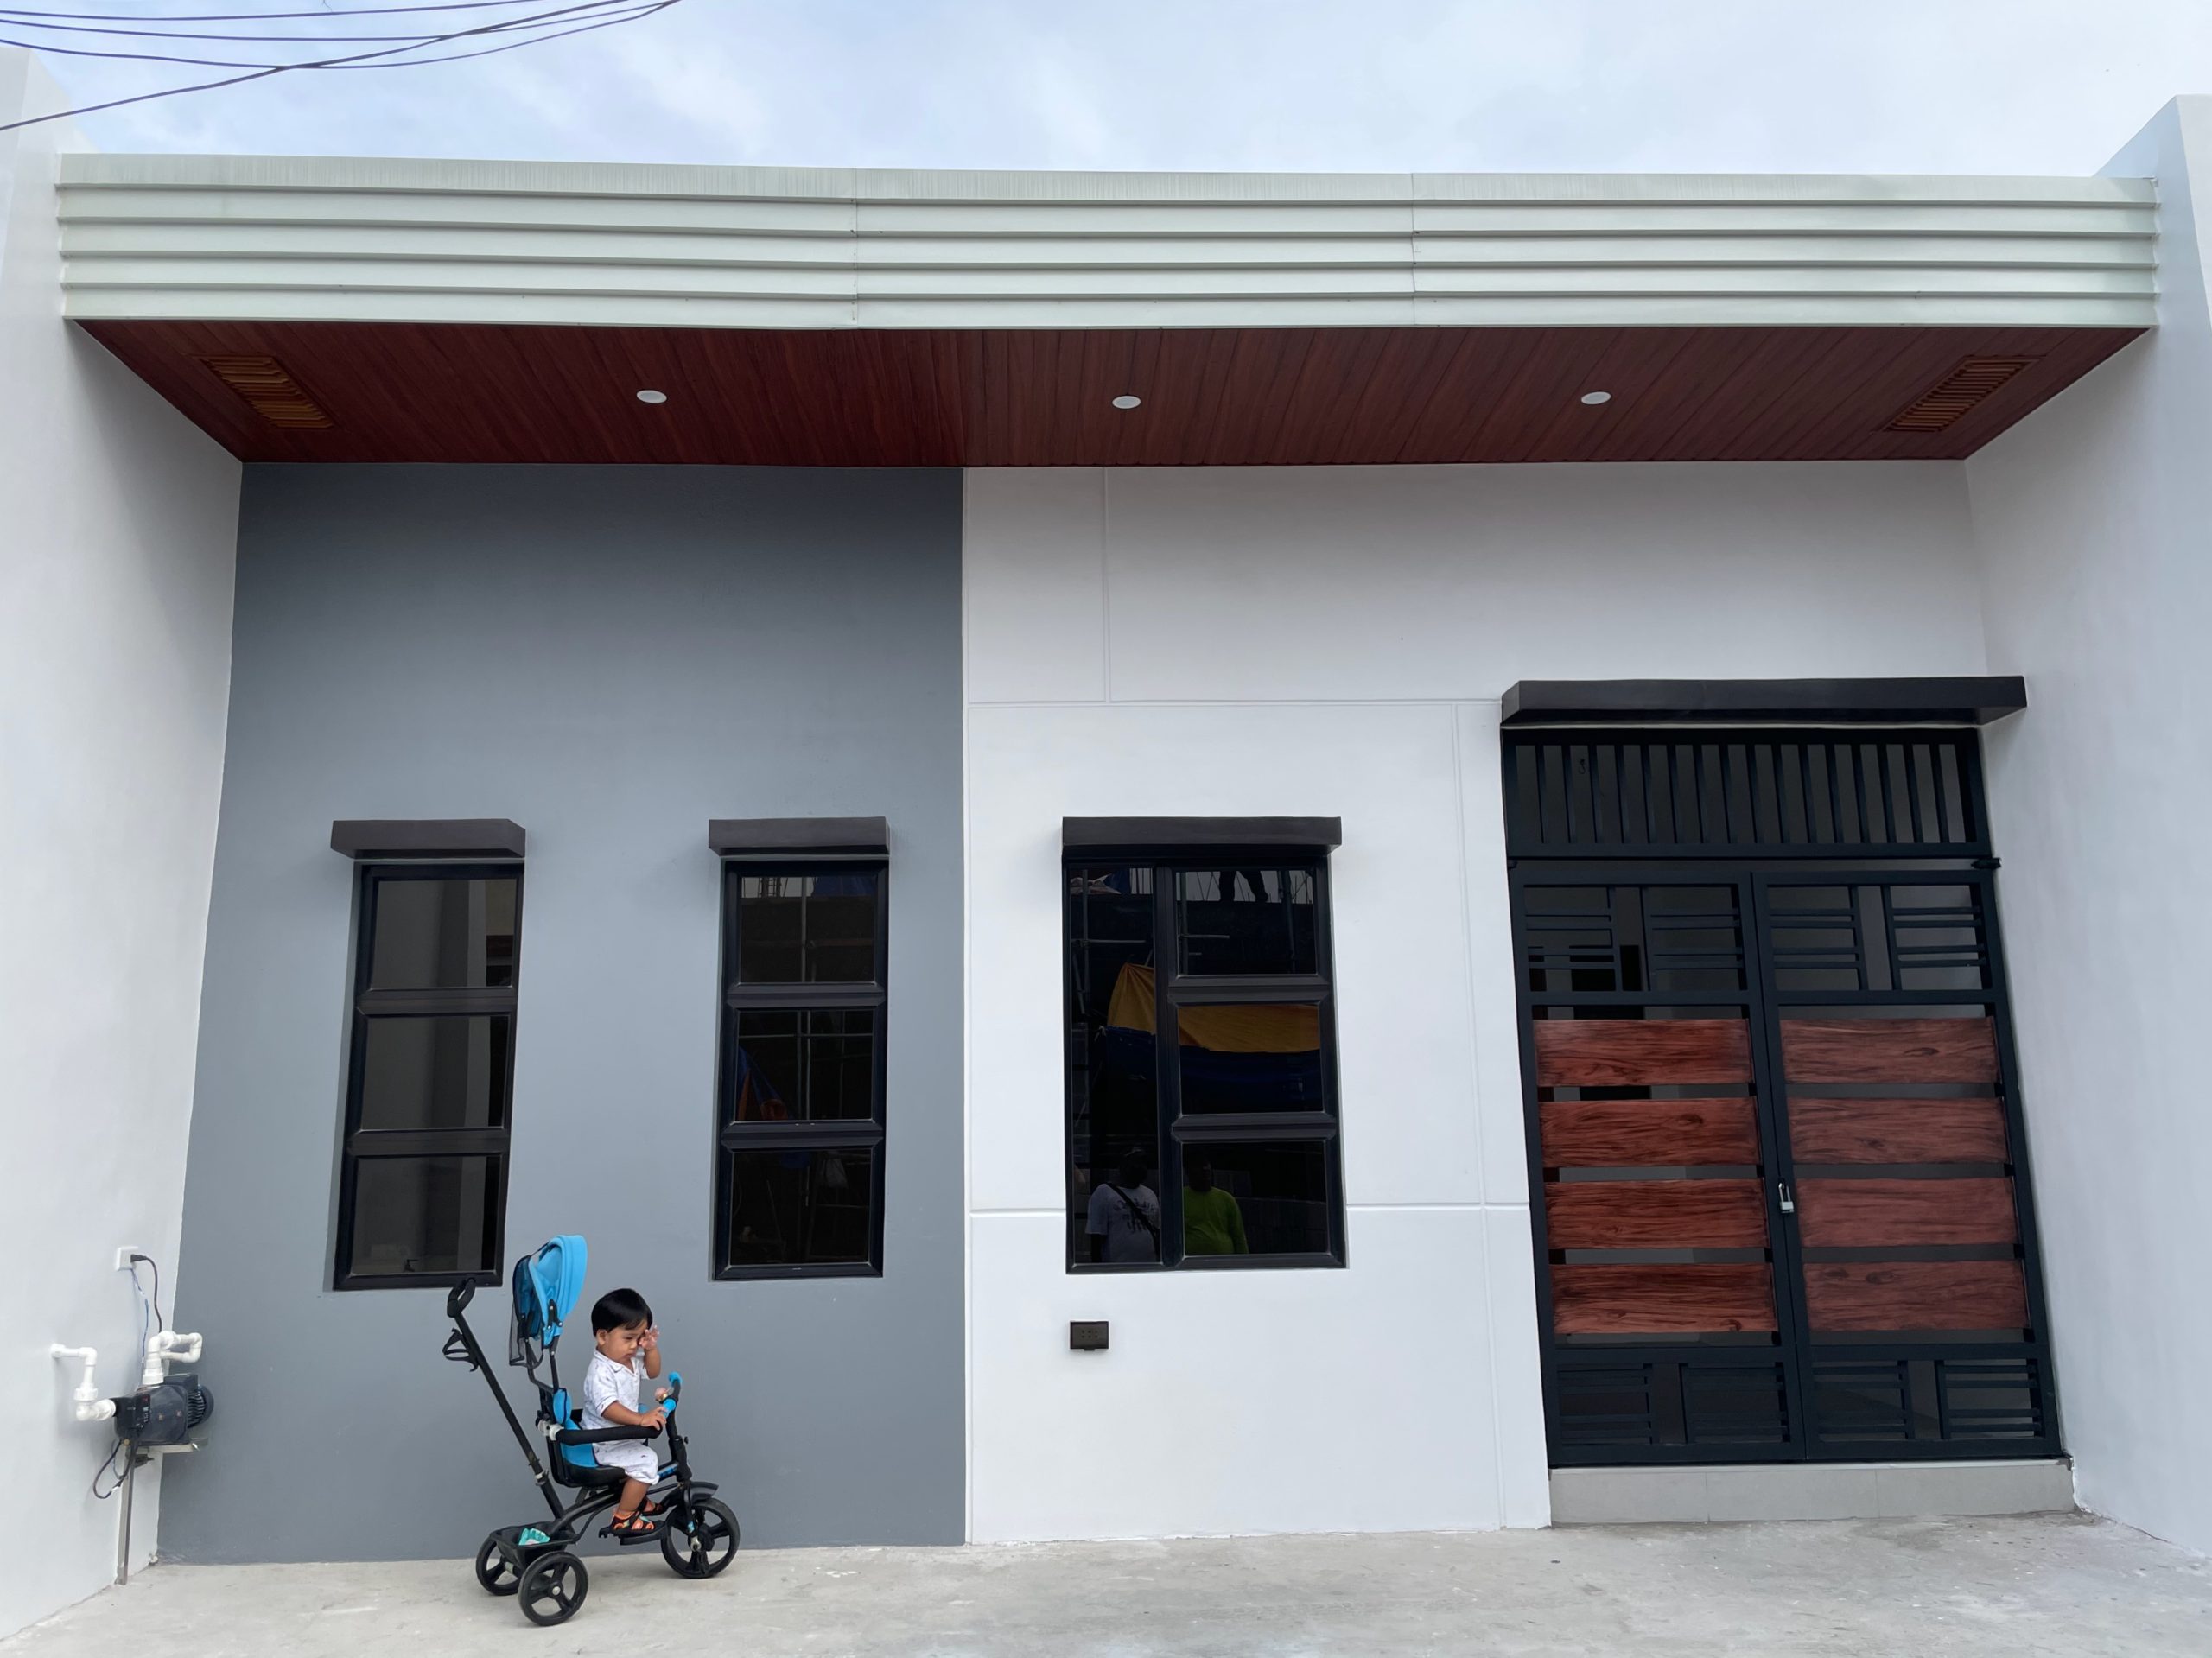
We’ve been incredibly blessed though. We got in a position where we can afford it. I also had a goal to purchase each of my kids a property while I still can. The idea is whatever happens to me, at the very least they’ll have a place of their own. But since they are still very young, we thought of trying to rent it out for the mean time.
We were able to purchase and rent-out our first property last year. That’s when it hit me why it was a good investment.
Investment options
When our savings started to grow, I started looking on where to put it. I knew that keeping it in a savings account will make its value slowly eaten by inflation (which is 2.64% last year). So I had this urgency to make it productive. These are the investment options I considered:
Pag-ibig MP2 is most often recommended because it has a high interest rate and relatively safe. It’s interest rate last year was 5.62% and it has a maturity of 5 years.
For our rental property, we were able to rent it out at 1% of the total cost. That’s an annual gross of 12%. Setting aside 2% for tax and maintenance. It earns 10% yearly. Higher than other safe investment options I considered. At the same time, the property itself appreciates in value overtime (I have no idea how to compute real estate appreciation though).
To be concrete, let’s say the property costs 1,000,000. And we’re able to rent it out for 10,000/month, that’s 120,000/year. Then set aside 20,000 for tax and maintenance, that will result to 100,000 net income yearly.
I remember getting shocked with my first credit card bill. Total amount is almost the same amount as my full-time job salary. 😅
That was 8 years ago.
Mabilis ako madala e. Soon after that, I looked up how to properly manage my money. This is when I found YNAB (You Need A Budget). It’s a budgeting software. Its value isn’t in the software itself, it’s in their methodology. It provided me structure on how I should think about money.
First phase is explicitly deciding where to put in all my money.
The goal here is to have an idea where my money is going. I can’t improve what I can’t measure right? Having a handy list of my budget, upcoming expenses, and current state of my net worth made it really easy to decide on unplanned purchases.
This also made me treat credit card spendings as money spent. It’s instantly deducted to my net worth as soon as I spend it.
Second phase is aging my money.
YNAB have this concept called “Age of Money”. It means how long your money stays with you before you use it.
I recently got to a point where my age of money reached 180 days. This gave me flexibility to plan ahead, take risks, and try new things.
Beyond YNAB
What I’m looking for to do next are investing on a business and stocks.
I’m like a sponge now absorbing information from r/phinvest. Taking action to things that’s starting to make sense to me.
I just sorted out all my debt and budgeted my remaining money yesterday and it felt I’m in control of my life! Haha
There’s this fresh start feature on YNAB that will hide all your previous, probably unaccounted, transactions. It eliminates the burden of what-has-been.
The idea is: you only need to think on what you have now and what will be your future spendings. You just can’t change anything to what was spent, just let it go and clear your mind of it.
Maybe it’s the same with blogging. I have been wanting to write for a long time, I was just waiting for my excuses to dry up haha.